Short answer: To file a Colorado roof storm-damage claim: document the damage and note the storm date, file directly with your carrier, attend the adjuster's inspection, then review the carrier's estimate. A good roofer documents thoroughly and, after a signed contract, discusses the repair scope with your insurer — but your carrier decides the claim, and nobody can promise approval.
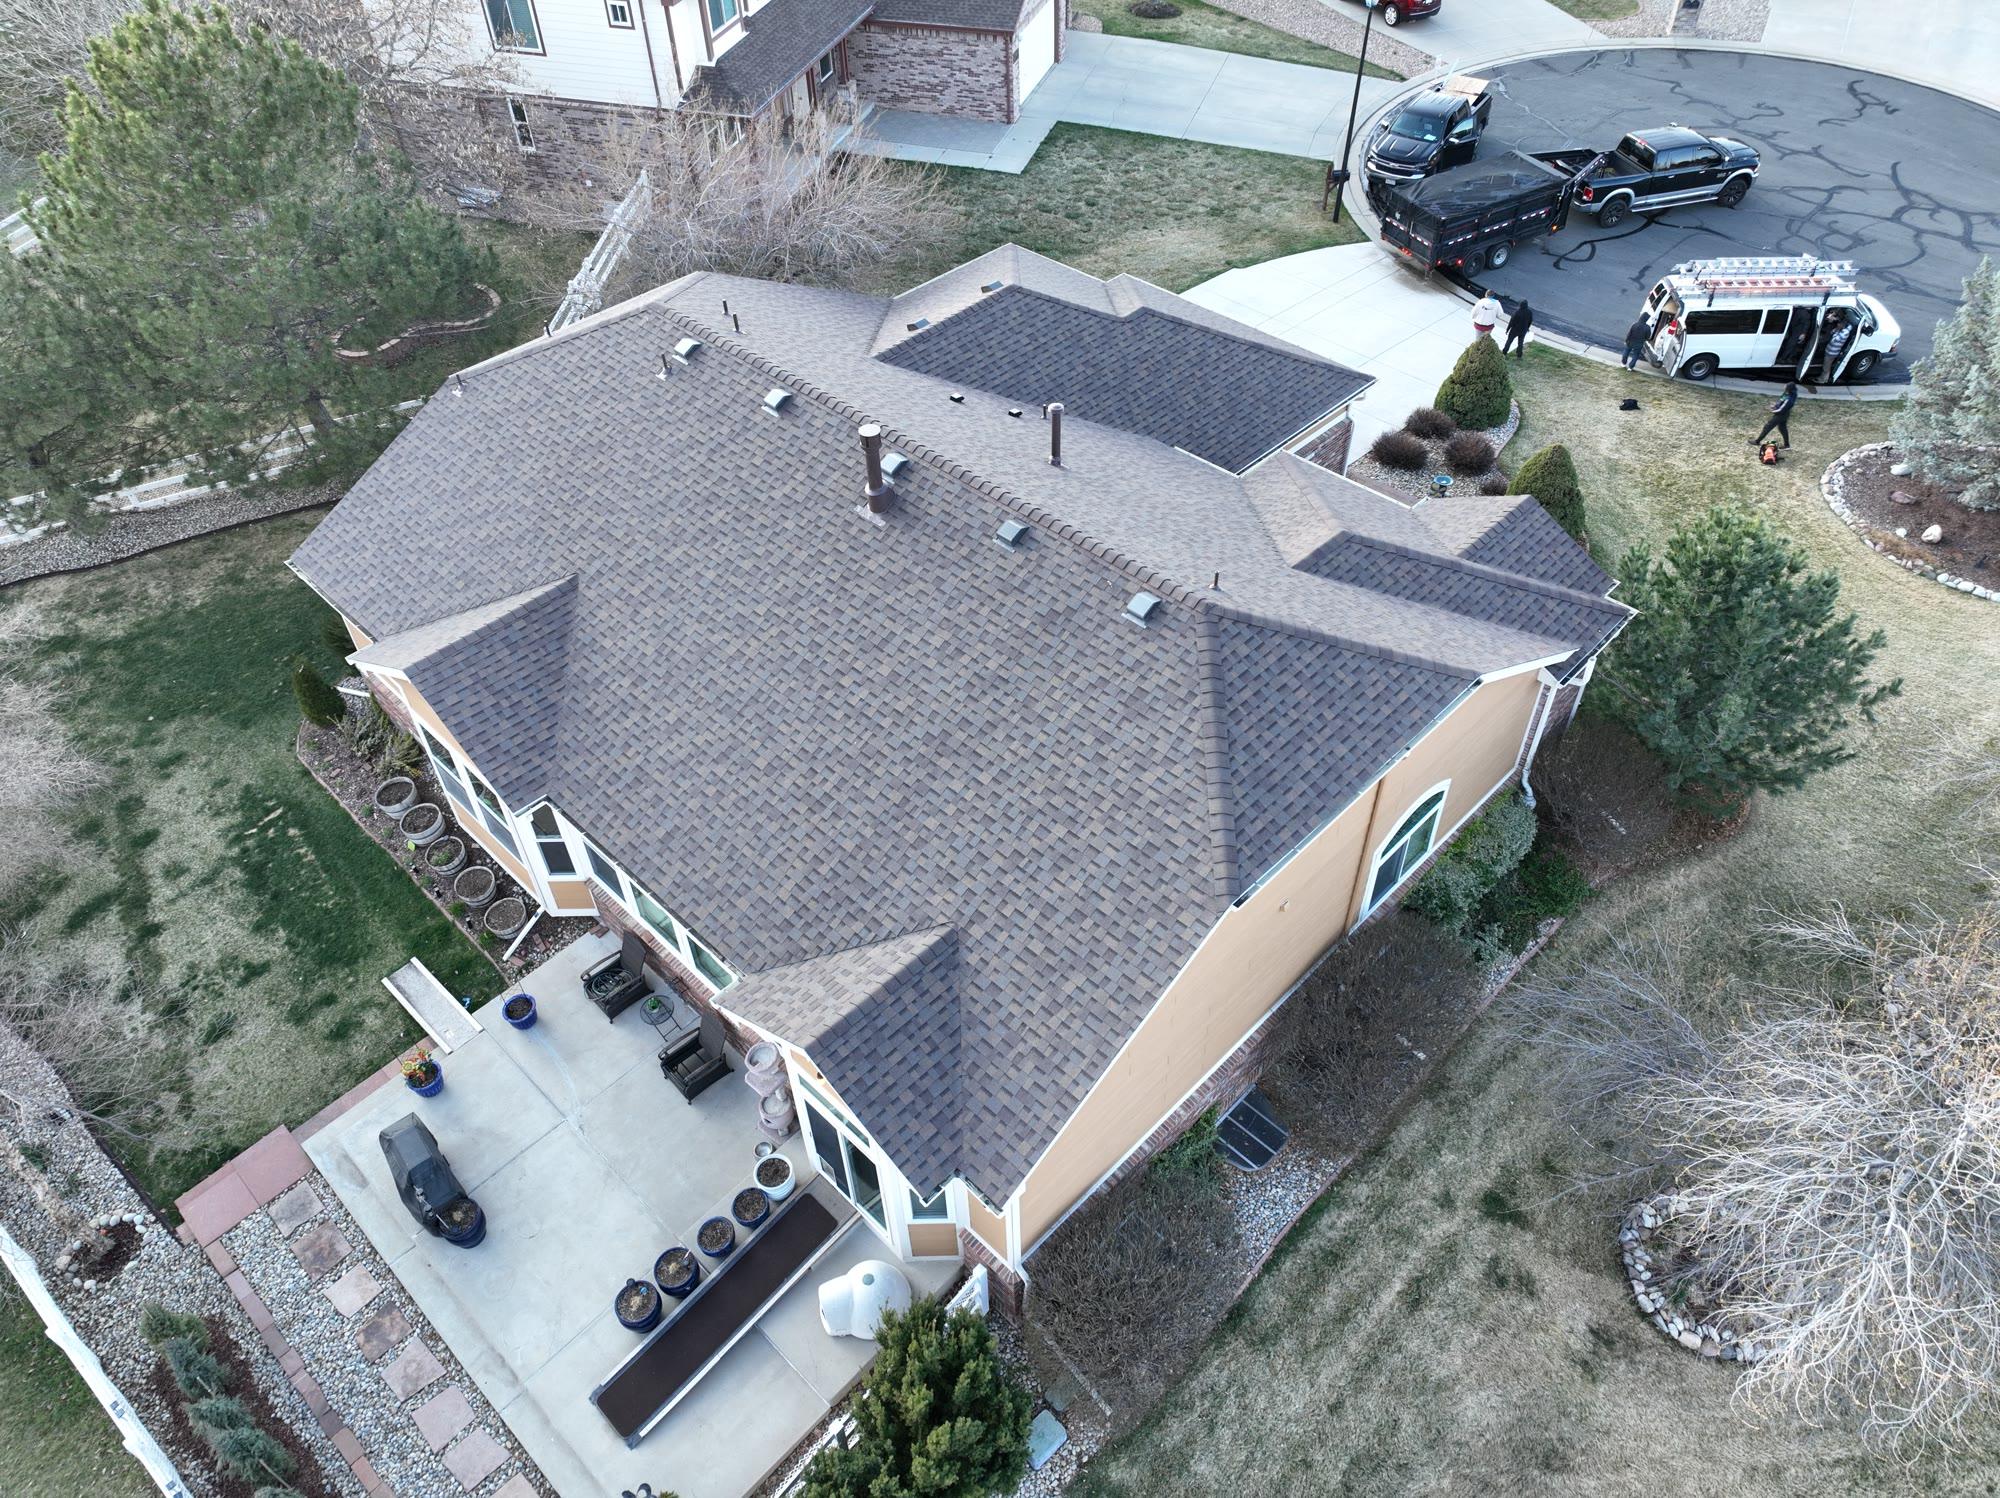
A storm rolls through, the wind picks up, and the next morning you're standing in the yard wondering whether your roof just took a hit. If you live anywhere along the Front Range, you've probably had this exact moment more than once. Colorado's Front Range is one of the most hail-prone regions in the country, and a single afternoon storm can quietly knock years off a roof's life.
The good news is that a storm-damage insurance claim is a process you can understand and walk through with confidence. The frustrating part is that nobody hands you the map. So here it is, plainly. We'll cover how to inspect and document, how to file with your carrier, what actually happens at the adjuster's inspection, and how estimates and supplements work. And we'll be honest about one thing up front: no contractor controls whether your claim is approved. The carrier decides. What a good roofer does is document what it finds on the roof, thoroughly and accurately.
Step 1: What should you document before you call anyone?
After a storm passes and it's safe, do a ground-level look first. You don't need to climb up, and honestly, you shouldn't. From the ground and from inside, watch for the telltale signs of hail and wind damage:
- Dented or dinged gutters, downspouts, and metal flashing, since soft metal shows hail strikes clearly
- Shingle granules collecting in gutters or pooling at the bottom of downspouts
- Cracked, bruised, or missing shingles, or shingles lifted and curled by wind
- Dents on roof vents, the AC unit, the garage door, or your car, which suggest the hail was large enough to do damage
- Water stains on ceilings or in the attic, which can show up days or weeks later
- Dings or splatter marks on the deck, fence, or window screens
Take photos and write down the date of the storm. The date matters, because many policies ask for prompt notice of a loss (policies vary — read yours and ask your insurer or agent), and a clear storm date helps your whole claim line up. If you're wondering how long you have, we wrote that up separately: your policy's notice window and Colorado's statute of limitations are two different clocks. If you're not comfortable assessing the roof yourself, this is exactly where a professional inspection helps. We offer free, no-pressure inspections so you know what you're actually dealing with before you ever pick up the phone with your insurer.
Step 2: How do you file the claim with your carrier?
If you decide to file, you do it directly with your insurance company. You're the policyholder, so the claim is yours to open, whether by phone, app, or website. Have your policy number, the storm date, and your documentation ready. The carrier will assign a claim number and schedule an adjuster to come out and inspect.
A few things are worth knowing before you file. Make sure you understand your deductible, since on many Colorado policies it's a percentage of your home's value rather than a flat dollar amount, which surprises people. Whether you can borrow that money is a separate question, and we answer it here: can you finance a deductible in Colorado? Also ask whether your policy pays Replacement Cost Value or Actual Cash Value, because that affects how depreciation gets handled. Policies vary — read yours and ask your insurer or agent, so you know what to expect. If you'd like a second set of eyes on the roof, we can document the damage; here's what we do (and don't do) on the insurance claim side.
Step 3: What happens at the adjuster's inspection?
The adjuster is the insurance company's representative who comes to assess the damage and decide what the policy covers. This visit matters, and once you've signed a contract with a roofer, they can discuss the repair scope with your insurer. That keeps the conversation grounded in what's actually up there.
On a storm restoration job where you've signed a contract with us, that conversation stays on the repair scope: we point out the documented damage and answer questions about how Colorado hail affects different roofing components. The adjuster still makes the call. Our job is to document what we find on your roof, completely and accurately.
Step 4: What is a supplement?
After the inspection, the carrier issues an estimate, which is their written breakdown of the approved scope and what they'll pay. If anything in it is unclear, ask your insurer or agent. This is where details matter, because the first estimate doesn't always capture everything a proper repair requires.
That's what a supplement is for. A supplement is a formal request to the carrier to revise the estimate when something legitimate was missed or underpriced. Common examples include:
- Damaged components beyond the shingles, like flashing, vents, ridge cap, or gutters and downspouts that took hail hits
- Code-required upgrades, such as ice-and-water shield or proper ventilation that current building code calls for
- Steep-slope or multi-story access that adds real labor the original estimate didn't account for
- Layers or decking issues that only become visible once the old roof is removed
Supplements aren't about padding a number. They're about matching the estimate to the real, code-compliant work the roof needs. After you sign a contract with us, we provide supplement documentation for that repair scope, whether the job ends up being a targeted repair or a full roof replacement.
What can a roofer actually do on a claim — and where is the line?
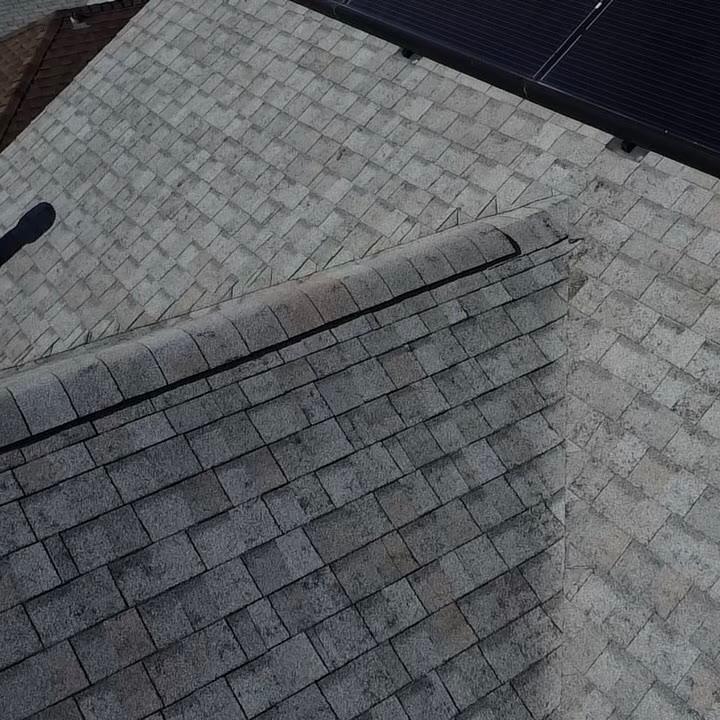
You can file and manage a claim entirely on your own, and plenty of homeowners do. Where an experienced, local roofer earns their keep is in the documentation. Thorough photos, a clear damage scope, and knowledge of how Colorado storms affect specific materials are the core of it; after you sign a contract, a roofer can also discuss the repair scope with your insurer, and that's where the line is. We're a small Parker-based team, serving the Denver metro and Front Range, not a crew that shows up after every storm and disappears before the work is done. You can check our service areas to confirm we cover your neighborhood.
And to be crystal clear one more time: the carrier owns the decision. We document what we find, and we do the work right. We never promise an approval, because that's not ours to give, and any honest roofer will tell you the same.
If a storm has you wondering about your roof, the simplest next step is a free, no-pressure inspection so you actually know where you stand. Reach out through our contact page or call (720) 544-3645, and we'll take a careful look. No obligation, no hard sell, just a straight answer about your roof.